Module 7 · Building & Testing a Complete Trading Strategy · Lesson 2
Backtesting a Trading Strategy: How to Find Out if Your Rules Actually Work
Learn how to test a rule-based trading strategy against historical price action, avoid hindsight bias, build a meaningful sample and collect the statistics needed to determine whether your setup shows a repeatable edge.
Backtesting
Historical Data
Sample Size
Expectancy
A strategy can sound excellent and still fail when tested.
That is exactly why backtesting matters.
Backtesting means taking the exact rules created in Lesson 1 and applying them to historical market data as if you were trading those conditions in real time.
The goal is not to prove that your strategy is good.
The goal of backtesting is to discover the truth about the strategy before real money forces you to discover it the expensive way.
A proper backtest should challenge your assumptions, expose weaknesses and produce data you can use to make better decisions.
Lesson Objectives
What You’ll Learn
✓ What backtesting actually measures
✓ How to test without hindsight bias
✓ How many trades to collect
✓ Which statistics matter most
✓ How to track drawdown and losing streaks
✓ How to avoid over-optimizing the test
What Is Backtesting?
Backtesting is the process of applying a fixed trading strategy to historical market data and recording what would have happened if the rules had been followed exactly.
Fixed Rules → Historical Data → Recorded Trades → Statistics → Evaluation
The emphasis is on fixed rules. If you change the strategy every time a historical trade loses, you are no longer testing one strategy.
What a Backtest Can Tell You
How often the strategy wins
How large the average winner is
How large the average loser is
How often losing streaks occur
What drawdown may look like
Which sessions or markets perform best
Whether certain filters improve results
Whether the overall system appears to have positive expectancy
What a Backtest Cannot Tell You
✕ It cannot guarantee future performance.
✕ It cannot recreate every live execution condition perfectly.
✕ It cannot guarantee the same spread or slippage.
✕ It cannot remove future market-regime changes.
✕ It cannot compensate for poor rule-following in live trading.
Backtesting gives evidence — not certainty.
Freeze the Strategy Before You Start
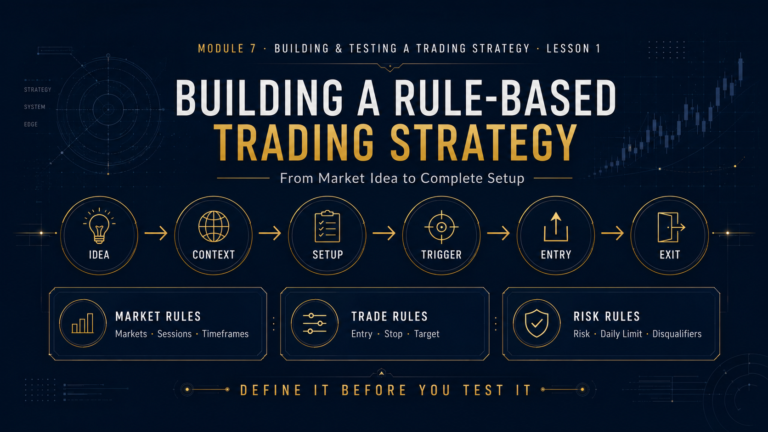
Before the first historical trade is reviewed, your Version 1 rules should already be written.
Market: Defined
Session: Defined
Context: Defined
Trigger: Defined
Stop: Defined
Target: Defined
Risk: Defined
Now you are testing the strategy instead of redesigning it one chart at a time.
The Biggest Enemy: Hindsight Bias
Historical charts make everything look obvious because you can already see what happened next.
You see price later rally 300 pips.
Suddenly the earlier long setup looks “obvious.”
You unconsciously interpret every ambiguous candle in favor of the trade.
Future information contaminates the historical decision.
Use Bar Replay When Possible
One of the best ways to reduce hindsight bias is to hide future candles and reveal price one bar at a time.
1. Choose an older historical period.
2. Hide candles to the right.
3. Advance one candle at a time.
4. Make decisions only from visible information.
5. Record the trade before revealing the outcome.
Trade the Past as if You Do Not Know the Future.
Test Chronologically
Move through the market in order rather than jumping around looking for attractive examples.
January → February → March → April → May
This forces the strategy to experience quiet periods, ugly periods and losing streaks — not just the beautiful examples you would choose for a screenshot.
Never Cherry-Pick Only the Best Setups
Strong winner? Record it.
Ugly loser? Record it.
Breakeven? Record it.
Setup qualified but looked uncomfortable? Record it.
If the rules say it qualifies, the test must include it.
Record Every Qualifying Signal
A proper backtest is not a gallery of favorite trades.
Qualifies + Winner → Record
Qualifies + Loser → Record
Qualifies + Breakeven → Record
Does Not Qualify → Skip
What Should You Record?
| Field | Why It Matters |
|---|---|
| Date | Allows chronological analysis |
| Instrument | Compare market performance |
| Session | Compare timing quality |
| Setup Type | Separate strategy variations |
| Direction | Long vs short performance |
| Entry | Execution reference |
| Stop | Defines 1R |
| Target | Measures planned reward |
| Result in R | Standardizes performance |
| Screenshot | Allows later visual review |
Measure Results in R-Multiples
R allows trades with different stop distances and account sizes to be compared consistently.
1R: Planned amount at risk
Full Loss: -1R
2:1 Target Hit: +2R
Half-R Winner: +0.5R
Breakeven: 0R
How Many Trades Should You Backtest?
There is no magic number, but very small samples can be misleading.
10 Trades
Far too small for strong conclusions.
30 Trades
Early information only.
50–100+
More useful for identifying patterns.
The more variable the strategy and market environment, the more valuable a larger sample becomes.
Test Across Different Market Conditions
Trending markets
Range-bound markets
High-volatility periods
Low-volatility periods
Different months and economic environments
A strategy that works only during one unusually strong trend may not be robust enough for general use.
Do Not Mix Markets Without Tracking Them Separately
EUR/USD: 80 trades
GBP/USD: 80 trades
XAU/USD: 80 trades
You may later combine results, but separate tracking allows you to see whether one market is carrying the entire strategy.
Statistic #1: Win Rate
Win Rate = Winning Trades ÷ Total Trades × 100
60 winning trades ÷ 100 total trades = 60% win rate
Win rate is important, but it means very little without average winner and average loser.
Statistic #2: Average Winner & Average Loser
Average Winner: +2R
Average Loser: -1R
A strategy can be profitable with a lower win rate if the average winner is sufficiently larger than the average loser.
Statistic #3: Expectancy
Expectancy estimates the average amount a strategy is expected to make or lose per trade across a large sample.
Expectancy = (Win Rate × Avg Win) − (Loss Rate × Avg Loss)
Win Rate: 45%
Average Winner: +2R
Loss Rate: 55%
Average Loser: -1R
Expectancy = +0.35R per trade
Statistic #4: Equity Curve
Add each trade’s R result in chronological order.
0R → +2R → +1R → 0R → +2R → +4R → +3R…
The equity curve shows not just whether the strategy made money, but how difficult the journey was.
Statistic #5: Maximum Drawdown
Maximum drawdown shows the largest decline from an equity peak to a later trough during the test.
Equity reaches: +18R
Then declines to: +10R
Maximum drawdown during that decline = -8R
A profitable strategy with extreme drawdown may still be unsuitable for your risk tolerance.
Statistic #6: Maximum Losing Streak
L → L → L → L → L → W
If your backtest shows five or six consecutive losses are normal, you should not be shocked when a similar sequence appears live.
Backtesting prepares you psychologically for the ugly parts of the strategy too.
Statistic #7: Profit Factor
Profit factor compares total winning profits with total losing losses.
Profit Factor = Gross Profit ÷ Gross Loss
Gross profit: 80R
Gross loss: 50R
Profit factor = 1.60
Statistic #8: Trade Frequency
Two profitable strategies can feel completely different if one trades twice per month and another trades twice per day.
Trades per week
Trades per month
Average time between setups
Average time spent in a trade
Break Results Down by Session
| Session | Trades | Win Rate | Net R |
|---|---|---|---|
| London | 60 | 58% | +24R |
| New York | 60 | 43% | +5R |
This may reveal that the core strategy works in both sessions but performs substantially better in one.
Break Results Down by Setup Type
Break & Retest: +18R
Liquidity Sweep Reversal: +11R
Range Breakout: -4R
Without setup labels, you might never discover that one variation is dragging down the rest.
Compare Long and Short Performance
Long Trades
55 trades · +21R
Short Trades
52 trades · +4R
Test Strategy Filters Separately
If you suspect a filter improves performance, test it objectively instead of simply assuming.
Version A: All qualifying setups.
Version B: Same strategy, but exclude trades near high-impact news.
Compare results using a meaningful sample before changing the official strategy.
Beware of Overfitting
Overfitting happens when rules are adjusted so specifically to historical data that they may not generalize well to new market conditions.
Strategy loses on Tuesdays.
Remove Tuesdays.
Then losses occur at 9:45.
Remove 9:45 setups.
Then losses happen when RSI is 56.
Rules become increasingly designed around the past instead of the trading idea.
A simpler strategy that survives many conditions can be more valuable than a perfect-looking historical curve built with dozens of filters.
Include Realistic Trading Costs
A backtest that assumes perfect execution can make marginal strategies appear better than they really are.
Spread
Commission
Slippage assumptions
Swap / financing where relevant
Realistic entry and exit prices
Watch Out for Intrabar Ambiguity
Historical candles can hide the order in which prices were reached inside the candle.
A candle may contain both your stop and your target. If you cannot determine which was hit first from the available data, do not automatically award yourself the winner.
Use lower-timeframe data where appropriate or apply a conservative rule.
Include Missed Trades If the Rules Would Miss Them
A retest-entry strategy will sometimes watch price leave without filling the order.
Breakout occurs.
Strategy requires retest.
Retest never happens.
Result: No Trade.
Do not convert it into a market entry afterward because you can see the trade would have won.
Do Not “Fix” Historical Losers
Historical trade loses.
You notice a tiny warning sign.
You decide that trade “would have been skipped.”
If the warning sign was not part of the original rules, the loss stays in the test.
Do Not Improve Historical Winners Either
If your rule says target 2R, a trade that later travels 8R is still recorded as +2R.
Rule: Fixed target 2R
Historical market later moves 8R.
Recorded result: +2R.
Example Backtest Summary
Strategy Version 1.0
Trades: 120
Win Rate: 46%
Average Winner: +2.1R
Average Loser: -1R
Expectancy: +0.43R
Profit Factor: 1.72
Maximum Losing Streak: 7 trades
Maximum Drawdown: -9R
Net Result: +51.6R
A Profitable Backtest Is Only the Beginning
Do not jump straight from a positive historical test to large live risk.
Backtest → Validate → Forward Test → Small Live Risk → Scale Gradually
Keep Some Data Out of the Development Process
One useful approach is to develop the strategy using one historical period and then test the final rules on a different untouched period.
Development Data
Used to build and refine the strategy.
Out-of-Sample Data
Used later to test whether the rules still behave well on unseen history.
What If the Backtest Is Bad?
That is useful information.
Discovering that a strategy does not work in a spreadsheet is cheaper than discovering it after risking real capital.
Review the data, identify specific weaknesses, create a documented Version 1.1 and test the new version separately.
Common Backtesting Mistakes
Looking at Future Candles
The outcome influences the historical decision.
Cherry-Picking Winners
Only attractive examples are included.
Changing Rules Mid-Test
Multiple strategy versions become mixed together.
Ignoring Trading Costs
Marginal edges can disappear after realistic execution costs.
Using Too Small a Sample
A handful of trades is treated as proof.
Overfitting the Rules
The strategy becomes too perfectly designed for the historical sample.
Ignoring Drawdown
Traders focus only on total return and overlook how difficult the strategy is to survive.
Complete Backtesting Framework
1. Freeze the strategy rules.
2. Choose a historical period.
3. Hide future candles where possible.
4. Move through data chronologically.
5. Record every qualifying trade.
6. Record results in R.
7. Include realistic costs.
8. Build a meaningful sample.
9. Calculate win rate and average R.
10. Calculate expectancy.
11. Measure drawdown and losing streaks.
12. Compare markets, sessions and setup types.
13. Avoid overfitting.
14. Test final rules on unseen historical data.
15. Document any changes as a new strategy version.
Test Before You Trust
Find Out What Your Strategy Really Looks Like Over 100 Trades
Financial Markets Academy offers live 1-on-1 mentorship for traders who want help developing rule-based strategies, testing them properly, reviewing statistics and building confidence from evidence instead of guesswork.
Backtesting Checklist
✓ Are the strategy rules frozen?
✓ Am I hiding future candles?
✓ Am I testing chronologically?
✓ Am I recording every qualifying signal?
✓ Am I recording losses honestly?
✓ Are results measured in R?
✓ Am I including realistic costs?
✓ Is the sample large enough?
✓ Have I measured maximum drawdown?
✓ Have I measured losing streaks?
✓ Have I calculated expectancy?
✓ Am I overfitting historical data?
✓ Have I kept unseen data for validation?
Frequently Asked Questions
What is backtesting in trading?
Backtesting is applying fixed strategy rules to historical market data and recording the hypothetical results to evaluate how the strategy behaved.
How many trades should I backtest?
There is no universal minimum, but larger samples such as 50–100 or more trades generally provide more useful information than very small samples.
What is hindsight bias?
Hindsight bias occurs when knowledge of what happened later influences how you interpret an earlier historical setup.
Does a profitable backtest guarantee future profits?
No. Historical performance does not guarantee future results, and live execution conditions can differ from historical testing.
What is expectancy?
Expectancy estimates the average gain or loss per trade based on the strategy’s win rate, loss rate, average winner and average loser.
What should I do if my backtest loses money?
Review the data, identify specific weaknesses, document any changes as a new strategy version and test that version separately rather than changing rules trade by trade.
Test Yourself
Module 7 · Lesson 2 Knowledge Quiz
1. What should happen before a backtest begins?
A. Freeze the strategy rules
B. Remove all losing setups
C. Increase risk
D. Look at future candles
2. What does bar replay help reduce?
A. Hindsight bias
B. All losses
C. Market volatility
D. Commission
3. What should you record during backtesting?
A. Every qualifying trade
B. Only winning trades
C. Only perfect setups
D. Only trades above 3R
4. Why is maximum drawdown important?
A. It shows how severe the strategy’s decline became during the sample
B. It guarantees future recovery
C. It measures spread
D. It determines leverage
5. What is overfitting?
A. Designing rules too specifically around historical results
B. Using a stop loss
C. Recording too many trades
D. Trading multiple sessions
Answer Key: 1. A · 2. A · 3. A · 4. A · 5. A
Key Takeaways
✓ Backtesting tests fixed strategy rules against historical data.
✓ The goal is discovery, not proving that your strategy is good.
✓ Hindsight bias can make historical charts look easier than they were.
✓ Bar replay helps simulate real-time decision-making.
✓ Every qualifying trade should be recorded.
✓ Larger samples provide more useful evidence.
✓ Win rate alone does not determine profitability.
✓ Expectancy combines win probability with average gain and loss.
✓ Maximum drawdown and losing streaks matter as much as total profit.
✓ Historical trading costs should be modeled realistically.
✓ Avoid optimizing rules around every historical loser.
✓ A profitable backtest should still be followed by validation and forward testing.
Coming Next
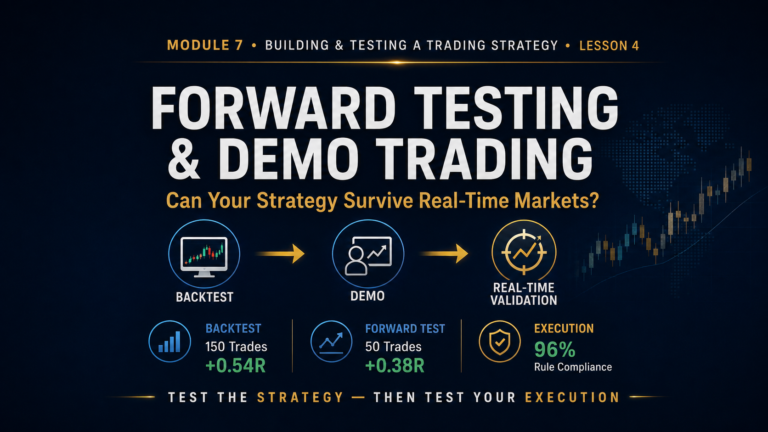
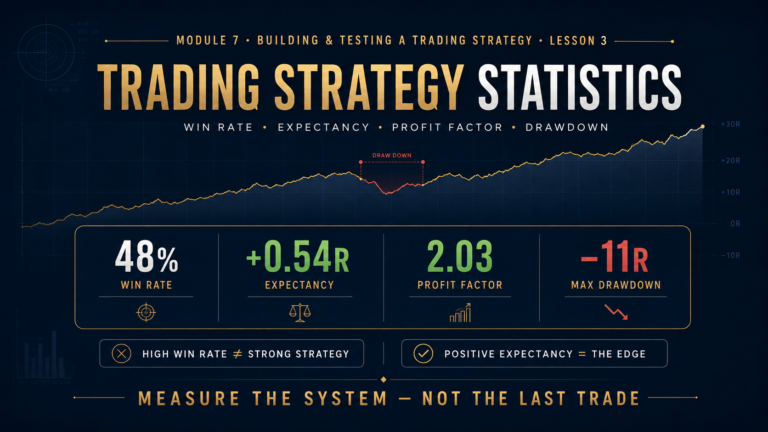
Lesson 3: Trading Strategy Statistics — Win Rate, Expectancy, Profit Factor & Drawdown
Next, we go deeper into the numbers that determine whether a strategy actually has an edge. You’ll learn how to calculate and interpret expectancy, break-even win rate, profit factor, average R, drawdown, losing streaks and why a high win rate does not automatically mean a better strategy.
Learn How to Measure Your Strategy →
Financial Markets Academy provides educational information only. Nothing in this lesson constitutes financial or investment advice or a guarantee of trading performance. Trading leveraged financial markets involves substantial risk and may not be suitable for everyone.